What does financial security look like once your working years end? For many people, the answer involves more than just having savings in the bank. Preparing your finances for retirement requires a thoughtful, comprehensive approach that considers healthcare costs, inflation, and your desired lifestyle. Without proper planning, even substantial savings can disappear faster than expected, leaving you vulnerable to financial stress during years when earning power diminishes.
1. Calculate Your Retirement Needs
The first step in retirement planning is understanding how much money you will actually need. Start by estimating your annual expenses in retirement, since many people assume they will spend significantly less once they stop working, but this is not always true. Healthcare costs, travel, hobbies, and home maintenance often consume more money than people anticipate. A common guideline suggests you will need 70 to 80 percent of your pre-retirement income to maintain your current lifestyle, though this varies based on individual circumstances.
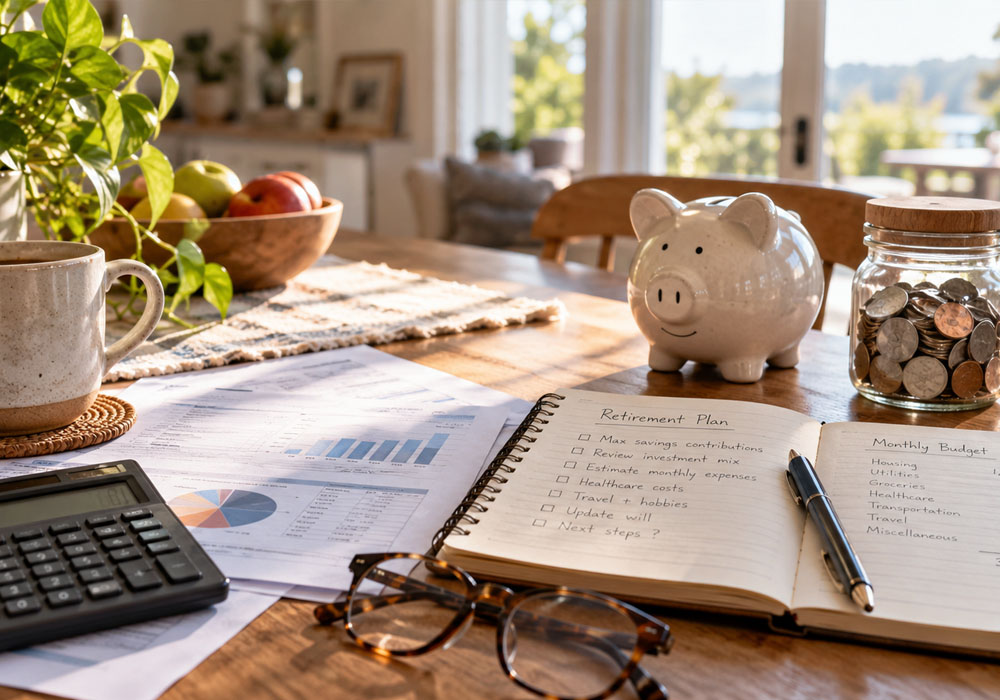
Make a detailed list of expected expenses, including housing costs, utilities, insurance premiums, food, transportation, and entertainment. Account for infrequent but significant costs such as home repairs, vehicle replacement, or helping family members financially. Once you have a realistic annual figure, multiply it by the number of years you expect to live in retirement. If you plan to retire at 65 and expect to live to 90, that represents 25 years of expenses to plan for, giving you a concrete target to work toward.
2. Maximize Your Retirement Account Contributions
Retirement accounts offer powerful tax advantages that can substantially accelerate wealth accumulation. If your employer offers a 401(k), 403(b), or similar workplace plan, contribute enough to capture any employer matching, since an employer match is essentially free money. Even if no match is available, these accounts allow you to save pre-tax income, which reduces your current tax burden while your money grows tax-deferred. Increasing contributions gradually, even by one percent of your salary each year, can add up to hundreds of thousands of dollars over several decades.
For those without employer plans or who want to save additional amounts, individual retirement accounts provide another valuable tool. Traditional IRAs allow tax-deductible contributions, while Roth IRAs let your money grow tax-free, with withdrawals also tax-free in retirement. The contribution limits for these accounts change periodically, so reviewing current rules ensures you are maximizing your available space. Starting early and staying consistent allows time and compound growth to do much of the heavy lifting.
3. Build a Diversified Investment Portfolio
How you invest your retirement savings matters as much as how much you save. A well-diversified portfolio spreads your money across different types of investments, reducing the risk that poor performance in any single area will derail your retirement. For most people, a mix of stocks and bonds is appropriate, though the exact balance depends on age, risk tolerance, and timeline. Younger workers can typically afford more stock exposure, while those closer to retirement may benefit from a higher bond allocation for stability.
Consider using low-cost index funds or target-date funds that automatically adjust their mix as you approach retirement. These options eliminate the need to constantly monitor individual stock picks and rebalance manually. Diversification also extends beyond stocks and bonds, as real estate through property ownership or real estate investment trusts can provide another layer of protection. Regular rebalancing ensures your portfolio maintains its intended balance and prevents overexposure to risk as market values change.
4. Account for Healthcare and Long-Term Care
Healthcare expenses represent one of the largest unknown costs in retirement. Medicare covers many basic medical needs for those 65 and older, but out-of-pocket costs for deductibles, copayments, and prescriptions can add up quickly, especially when facing serious health challenges. Long-term care such as nursing home or in-home assistance is not covered by Medicare and can cost tens of thousands of dollars annually. Many retirees are surprised to discover how much they will spend on health-related expenses.
Contributing to a Health Savings Account, if you have access to a high-deductible health plan, is one effective strategy. These accounts offer triple tax advantages: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. Unlike Flexible Spending Accounts, HSA funds roll over year to year and can be invested for growth. Long-term care insurance is another option worth exploring, and speaking with a financial advisor can help clarify whether it fits your situation or whether existing assets could cover these expenses if they arise.
5. Review and Adjust Your Plan Regularly
Retirement planning is not a one-time event but an ongoing process that should adapt as your life and circumstances change. Review your retirement plan at least annually, checking whether your savings are on track and adjusting contributions if your income or goals shift. Major life events such as inheritance, marriage, job changes, or health issues may require significant modifications, and changes in tax laws or investment performance can also affect your retirement readiness.
Working with a financial advisor to stress-test your plan against various scenarios, such as market downturns or longer-than-expected life expectancy, strengthens your overall strategy. Incorporating retirement income planning into these reviews helps ensure that withdrawal strategies and tax optimization decisions work together to maximize the longevity of your savings. As you approach retirement, your reviews should grow more detailed and focused. Consulting a tax professional in the years leading up to retirement can further reduce your tax burden and improve your financial outcomes.
Conclusion
Preparing your finances for life after work is a multi-faceted undertaking that requires honest assessment, strategic action, and ongoing attention. By calculating your retirement needs, maximizing contributions to tax-advantaged accounts, building a diversified portfolio, accounting for healthcare costs, and regularly reviewing your progress, you create a robust framework for financial security. The specific steps you take will depend on your age, income, goals, and personal circumstances, but the fundamental principle remains constant: intentional planning today creates options and freedom tomorrow. Even modest progress compounds meaningfully over time, and your future self will benefit from the effort you invest now.