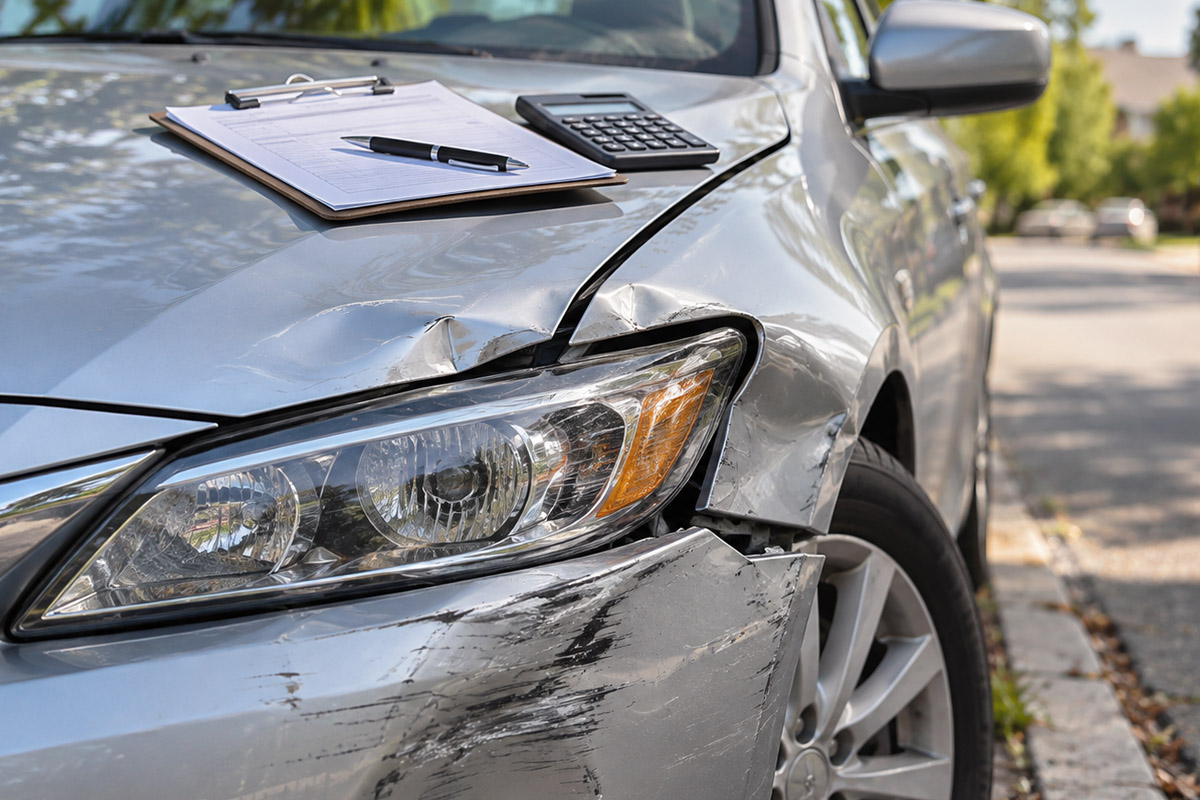
Two drivers walk away from the same intersection crash. One collects a check that covers a replacement vehicle, rental costs, and three months of lost income. The other accepts a number that barely covers the tow bill. The difference usually is not luck. It is what each driver handed the adjuster in the first two weeks.
You can control most of that. Below is how adjusters actually build a settlement number, where the gaps show up, and the steps you can take before you sign anything.
What an adjuster is really calculating
Adjusters work from a formula, even if they never show it to you. Special damages cover the bills you can prove, such as vehicle repair, medical treatment, and lost wages. General damages cover the harder stuff, like pain, inconvenience, and the way a shoulder injury changes how you sleep. Most offers you see are a blend of the two, adjusted by who the insurer thinks was at fault.
The formula matters less than the input. An adjuster cannot pay for a bill that does not exist on paper. If you paid cash for a chiropractor visit and never kept the receipt, that expense sits at zero in their file. Document everything starting the day of the crash.
Fault changes the math more than anything else. According to crash data tracked by the National Highway Traffic Safety Administration, human choices, not mechanical failures, cause the overwhelming majority of crashes. That means fault usually lands on a driver, and the percentage assigned to you comes straight out of your check.
Why the first offer is almost never the final one
Insurers open low. That is not cynicism, it is how the claims model works. The first number is a test: accept it and the file closes cheap, push back with evidence and the number moves. I have seen gaps of thousands of dollars between the opening offer and the eventual settlement on claims with identical injuries.
What moves the number is documentation that contradicts their assumptions. A repair estimate from a shop they did not choose. A doctor’s note describing restrictions, not just a diagnosis. A wage statement showing the shifts you missed. Each piece closes a hole the adjuster was using to discount you.
Timing matters too. Insurers track how quickly claims resolve. A claim sitting open for months costs them money, which is one reason a well-documented file gets attention faster than a vague one. Silence is not your friend here, but neither is calling daily.
Three myths that quietly shrink settlements
Myth one: the adjuster is on your side. They are polite, they call back, and they work for the company writing the check. Those things can all be true at once. Myth two: you need to give a recorded statement right away. You do not, and a rushed statement becomes the quote they use to argue your injury was pre-existing. Myth three: a settlement is final once you cash it. It is. Signing a release typically ends your ability to reopen the claim, even if a hidden injury shows up later.
Here is a point worth sitting with. Adjusters handle dozens of files a week, and yours is one line on a spreadsheet to them. To you it is the difference between recovering and struggling. That asymmetry is exactly why the file needs to be built as if no one else will build it for you.
The Green Book method: building your own claim file
I call it the Green Book because a colleague kept her crash materials in a green three-ring binder, and the name stuck. The idea is simple: you keep one organized record of everything, so any adjuster, doctor, or attorney can understand your claim in ten minutes.
- Day one: Photograph every vehicle angle, the road, the weather, and any visible injury. Save the photos to cloud storage, not just your phone.
- Week one: Get the police report number and the other driver’s insurance details. Write down what you remember before it fades.
- Week one through treatment: Keep every receipt, discharge paper, and appointment slip in one place.
- Ongoing: Log missed work, canceled plans, and tasks you could not do. A short daily note beats a vague memory.
- Before any offer: Compare the offer against your actual costs, line by line, and list what is missing.
The binder matters because memory is unreliable and adjusters know it. A file with dated entries reads as credible. A verbal account three months later reads as negotiable.
When to bring in help, and what to expect
Not every claim needs an attorney. A fender bender with a clean police report and a two-week recovery can often settle fine on your own. The calculus shifts when injuries are serious, fault is disputed, or the insurer keeps lowballing a documented file.
Serious crashes are not rare. Data compiled by the Insurance Information Institute shows that millions of people are injured in motor vehicle crashes in the United States each year, and the resulting claims regularly involve disputes over who pays and how much. When those disputes harden, local representation tends to change the pace of the conversation. Drivers in the Aiken area often start by talking with Aiken car wreck attorneys, who handle the back and forth with adjusters while the driver focuses on recovery.
What changes when a lawyer steps in? Generally three things. The insurer stops calling you directly. Medical records and wage documentation get requested and organized as a package. And the demand letter arrives with a number supported by evidence instead of a figure you guessed at. You keep control either way. Ask about fees up front, understand that most injury firms work on contingency, and never let anyone rush a release.
A quick self-check before you accept anything
Run this list against your file. Have you finished treatment, or are you still being seen? Are all bills accounted for, including the ones you paid yourself? Does the offer cover lost income, not just medical costs? Is fault documented by a report rather than a story? Do you understand what the release gives up?
If any answer is no, do not sign yet. Ask the adjuster for the breakdown in writing. If they cannot explain how they reached the number, that tells you something useful. Claims reward preparation and punish guesswork. Start your file today, keep it current, and treat every conversation with an insurer as something worth writing down afterward. The one question that matters most is simple: does the final number actually make you whole, or does it just close the file?